All Categories
Featured
How to Maintain a Leading Advantage in 2026
Instead of marking a cyclical rebound, 2026 is increasingly considered as a consolidation year, in which diversification-led development ends up being more deeply embedded in the area's economic model, decreasing reliance on hydrocarbons and increasing resilience to external shocks. Projections from major institutions broadly converge on a stronger GCC growth profile in 2026 than in 2025, supported by resistant domestic demand, continued non-oil growth, and (to differing degrees) a firmer hydrocarbon contribution.
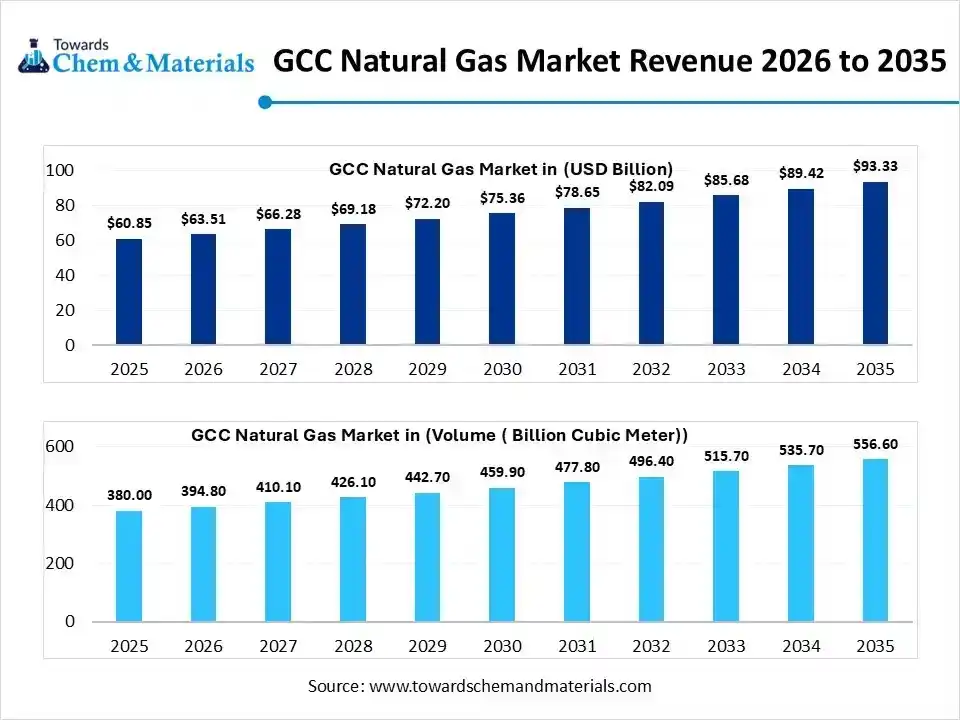
The World Bank, on the other hand, projects 3.2 percent growth in 2025, speeding up to 4.5 percent in 2026. The IMF Sees momentum improving, with GCC output development forecasted to rise from 1.7 percent in 2024 to 3.3 percent on average in 2025, reflecting a shift towards more favorable total conditions.
The IMF's World Economic Outlook (October 2025) tasks international growth easing to 3.1 percent in 2026, with sophisticated economies around 1.5 percent and emerging market and developing economies just above 4 percent. On that comparison, a 4.44.5 percent GCC growth would position the region materially ahead of the world average and a little above (or broadly in line with) the emerging-market aggregate, strengthening the GCC's status as a fairly high-growth pocketprovided that regional threat conditions remain consisted of and reform momentum holds.
Data from the GCC Statistical Center show that non-oil sectors already represent more than 73 percent of total GDP, a share that has actually continued to increase as federal governments expand financial investment in services, facilities, and technology. According to Oxford Economics, non-energy activity across the GCC is predicted to grow by around 4.1 percent in 2026, supported by strong labor markets, enhancing credit conditions, and increasing financial investment in innovation and AI-related infrastructure.
Analysing 2026 Market Data for Future Insights
Public-sector investment and reform remain central to sustaining this trend. Policy steps targeted at attracting foreign direct financial investment, reducing foreign ownership guidelines, expanding capital markets, and supporting private-sector involvement continue to underpin non-oil growth and lower the region's exposure to oil rate volatility. While hydrocarbons no longer control the growth outlook, oil incomes are anticipated to play a supportive role in 2026.
Oxford Economics expects Brent crude prices to fall listed below USD 60 per barrel in early 2026, restricting the near-term contribution of oil extraction to GDP. Oil supply is anticipated to rise again in the second half of the year, with a complete loosening up of staying production caps most likely by mid-2027.

Macroeconomic conditions across the GCC remain broadly helpful of growth. Inflation is expected to stay low, with the IMF forecasting average inflation of 2 percent throughout the region in 2026. Steady rates are helping protect genuine family incomes and underpin consumer costs, which Oxford Economics expects to grow by an average of 3.5 percent over 20262027.

Latest Posts

Key Advantages of Strategic Excellence for 2026
Comparing Innovative Models Against Traditional Frameworks
Leading Organizational Change in Modern GCC